Bank of Kigali joins China’s CIPS payment network: what it changes for Rwandan importers
The first bank in East and Central Africa to become a direct participant in China’s yuan payment system, Bank of Kigali promises faster, cheaper settlements with Rwanda’s top trading partner.
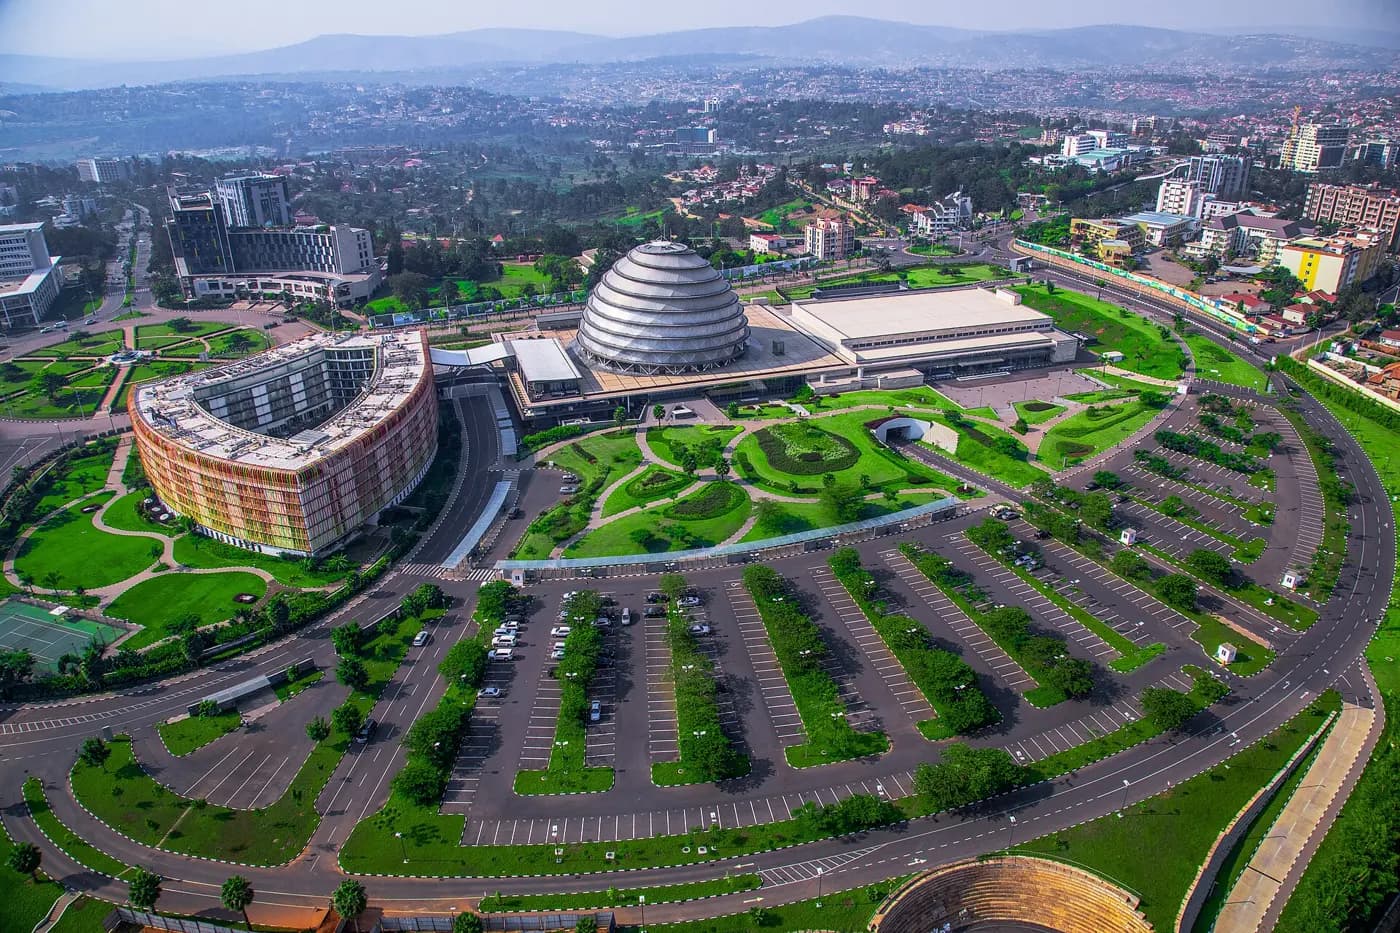
- On 8 September, Bank of Kigali became a direct participant in CIPS, China’s yuan payment system.
- It is the first bank headquartered in East or Central Africa to obtain this status.
- China accounted for 26.7% of Rwanda’s imports in the first quarter of 2026.
- The goal: faster, cheaper yuan payments, without replacing the dollar or SWIFT.
On 8 September 2026, in Xiamen, in south-eastern China, Bank of Kigali’s chief executive, Diane Karusisi, signed the agreement that makes Rwanda’s largest bank a direct participant in CIPS, China’s Cross-Border Interbank Payment System. The signing took place at the system’s second bank-business cooperation meeting.
It is a first for Rwanda, and for the whole region: no bank headquartered in East or Central Africa had this status before. The announcement, which went relatively unnoticed outside financial circles, nonetheless says a lot about how trade between Africa and China is evolving.
CIPS in a nutshell
CIPS (Cross-Border Interbank Payment System) is the infrastructure launched in 2015 with the backing of the People’s Bank of China to clear and settle international payments in renminbi, the Chinese currency, whose unit is the yuan. Until now, a Rwandan bank that wanted to pay a Chinese supplier in yuan had to go through several intermediary banks, often located in other countries, each taking fees and adding delays.
A direct participant processes its yuan transactions in the system itself. For its customers, that should mean faster payments, fewer intermediaries and therefore lower fees. CIPS is not a head-on competitor to the SWIFT banking messaging network: it uses compatible formats, and banks can connect to it without overhauling their systems.
China, Rwanda’s top supplier
The commercial logic is obvious. Trade between Rwanda and China reached $1.76 billion in 2024. In the first quarter of 2026, China accounted for 26.7% of Rwanda’s imports, or $355.5 million, and 25.8% of its exports, or $95 million. Machinery, building materials, electronic equipment, textiles: much of what Rwanda imports comes from China.
Rwanda–China trade in the first quarter of 2026
Source: Data cited by KT Press
Today, most of this trade is invoiced and settled in dollars. A Rwandan importer therefore buys dollars with Rwandan francs, then pays the Chinese supplier, who converts the dollars into yuan. Every conversion has a cost. Being able to pay directly in yuan, through a local bank connected to the Chinese system, removes a step.
What it changes in practice
- For an importer: a direct channel to pay Chinese suppliers in yuan, with in principle fewer intermediaries and lower fees.
- For an exporter: the possibility of being paid in yuan by Chinese buyers through a bank connected to the system.
- For the bank: a value-added service for its corporate customers, and a distinctive place in the regional market.
- For the country: diversified payment channels, currently heavily dependent on the dollar.
The bank promises simpler, faster and more connected international payments. The reality will be measured by concrete factors: the cost of a yuan transfer compared with a dollar transfer, the settlement time, and above all the availability of yuan. To pay in yuan, you have to have some or be able to buy them at a reasonable price, which requires an active foreign exchange market between the Rwandan franc and the Chinese currency.
Less dollar, no rupture
Bank of Kigali’s membership is part of a broader trend: China is encouraging the international use of its currency, and many countries in the Global South are seeking to reduce their dependence on the dollar, whose periodic shortages have penalised African importers in recent years. Several African banks, notably in southern and West Africa, are developing yuan payment services.
This should not, however, be seen as a rupture. The dollar remains the dominant currency of world trade and of African states’ debt. CIPS works alongside SWIFT, not against it. For a country like Rwanda, it is about adding an option, not changing sides. Rwanda’s exports to China, three times smaller than its imports, also limit the amount of yuan the country naturally earns.
A payment, before and after
Take a Kigali importer buying solar panels from a Chinese manufacturer. Today, in most cases, they ask their bank to convert their Rwandan francs into dollars, then send a dollar transfer. That transfer goes through a correspondent bank, often in the United States or Europe, which passes it on to the supplier’s bank in China. The supplier receives dollars and converts them into yuan. Two conversions, several intermediaries, fees at each step and sometimes several days’ delay.
With a bank participating directly in CIPS, the chain can be shortened: the importer buys yuan from their bank, which pays the supplier directly within the Chinese system. One conversion instead of two, fewer intermediaries. The gain will depend on the exchange rate offered between the Rwandan franc and the yuan, which remains the key point: if that rate is unfavourable, the savings on fees disappear.
Compliance questions
CIPS also has a geopolitical dimension. Some Western observers see it as a way for sanctioned countries to bypass the dollar-dominated financial system. For a bank like Bank of Kigali, which also works with American and European correspondents, this calls for particular vigilance: every transaction must comply with international anti-money-laundering rules and sanctions regimes, or its other banking relationships could be put at risk. Nothing suggests any difficulty at this stage, but it is a factor the bank will have to manage.
A signal for the region
Rwanda has for years presented itself as a regional financial platform, with the Kigali International Financial Centre. Being home to the first bank in East and Central Africa connected directly to CIPS reinforces that image, and could attract companies in the region that trade with China. Kenyan, Tanzanian or Ugandan banks, whose countries are also major importers of Chinese products, could follow.
For individuals, the effect will be more indirect. Rwandan students in China, traders who stock up in China’s big wholesale markets or families sending money could eventually benefit from yuan transfer services offered by the bank. But these offers have yet to be built. Initially, it will be importing companies, used to international transfers and letters of credit, that are the first users.
For Rwandan importers, the test will be simple: in six months, will paying a supplier in Guangzhou or Yiwu be cheaper and faster than today? If the answer is yes, the system will find its users without any promotional campaign. If it is no, membership will remain a diplomatic symbol more than a business tool.
- Bank of Kigali Joins China’s Cross-Border Payments System, First in This Region, KT Press.
- Bank of Kigali Joins China’s CIPS Payment Network, Kenyan Wall Street / Khusoko.
- Rwanda’s Biggest Bank Joins Chinese Payment System, The China-Global South Project.
- Bank of Kigali Joins China’s Interbank Payment System, TechMoran.
Spotted an error? Write to infos@novotech.blog. Corrections are flagged at the end of the article.