Only one mobile money account in four is used each month, a white paper warns
Owning an electronic wallet is not enough to join the financial system. A white paper relayed by CIO Mag puts a number on the gap between accounts opened and accounts in use, and proposes four workstreams to make mobile money an everyday tool.
Why it mattersYour mobile money number is only worth something if you use it to pay, save or borrow. That is the shift operators and regulators, the BCEAO among them, are trying to bring about.
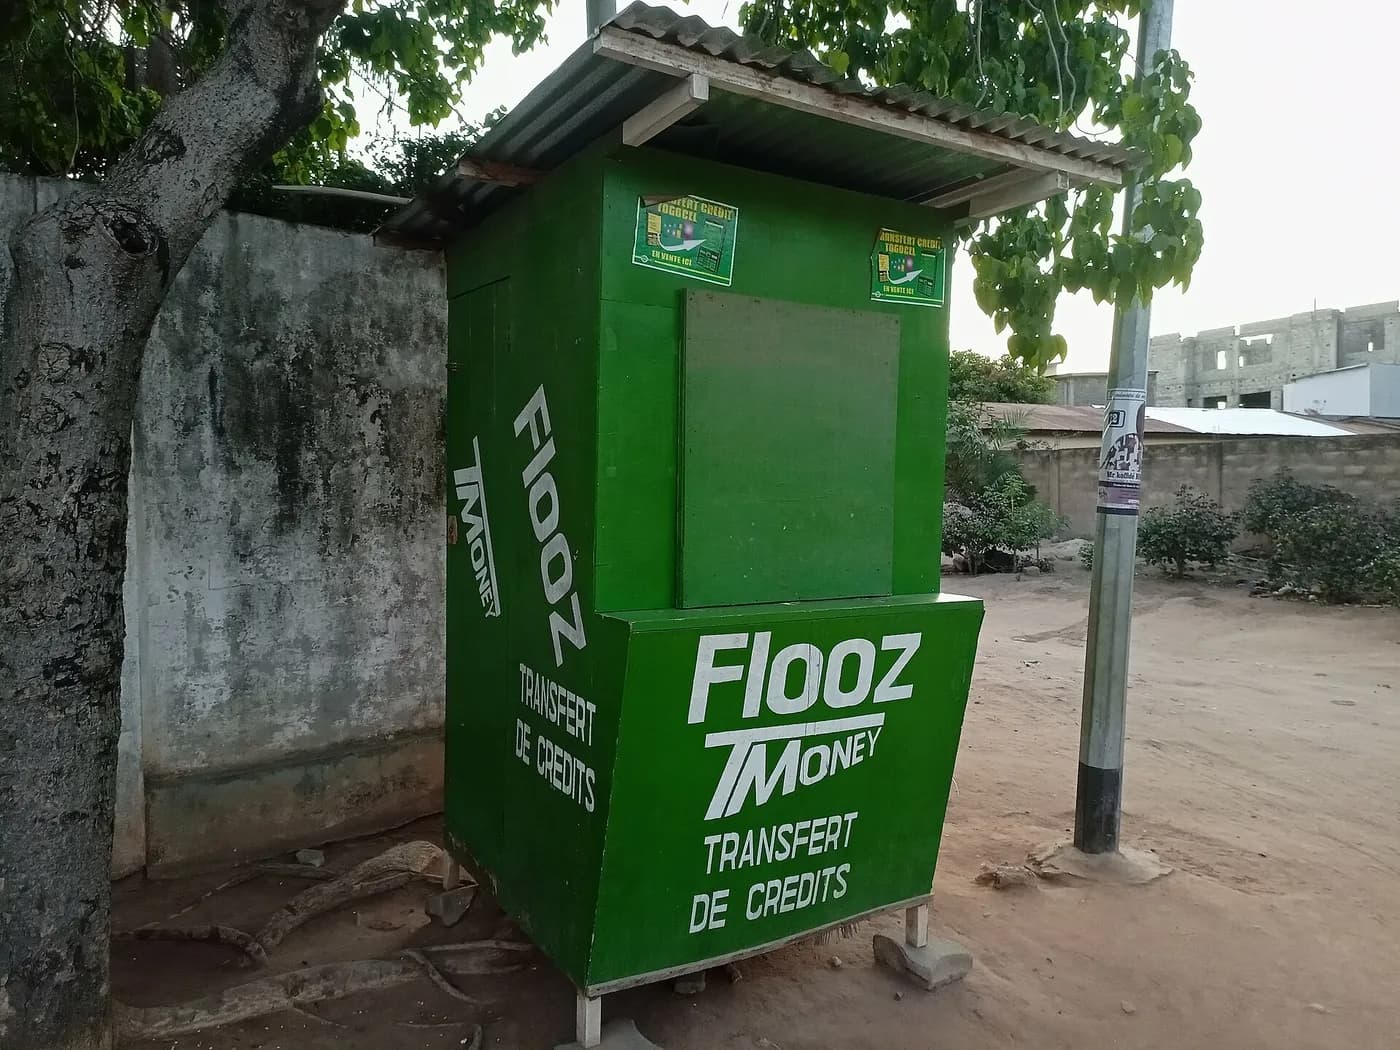
- According to a white paper whose findings CIO Mag published on October 20, 2026, barely one mobile money account in four is used each month.
- Worldwide in 2025: 2.3 billion accounts, 593 million active within 30 days, more than $2.1 trillion in transactions.
- The authors propose four workstreams: a proportionate regulatory framework, open infrastructure, everyday uses, and trust and security.
- Senegal appears only through Orange Bank Africa (more than 3 million customers in Côte d’Ivoire and Senegal); most of the figures carry no named source.
Two point three billion registered accounts worldwide in 2025, of which 593 million were active at least once in the previous 30 days: the gap is striking. Those figures come from a white paper whose findings CIO Mag published on October 20. The conclusion: barely one mobile money account in four is used each month. The first two numbers match the GSMA’s 2026 report, the global association of mobile operators, which also puts 2025 transactions at more than $2 trillion.
The movement is still massive. According to the text, 61% of adults in low- and middle-income economies made or received digital payments in 2024, against about 35% ten years earlier. In sub-Saharan Africa, 40% of adults had a mobile money account in 2024, up from 27% in 2021. But mobile money has stopped being an innovation: it has become infrastructure, and the authors argue that the challenge has changed in nature.
Access still too expensive, users who hesitate
The obstacles are first of all material. In 2025, 21% of people in rural Africa used the internet, against 55% of city dwellers; in 2024, an entry-level 2 GB data plan cost 4.2% of gross national income per capita on the continent, more than double the Broadband Commission’s 2% target. Women are 8% less likely than men to own a phone and 14% less likely to use mobile internet.
They also come down to trust. Nearly 30% of account holders in sub-Saharan Africa cannot use their account on their own, a share that rises to 46% in Malawi. And according to the SIIPS 2025 report cited in the white paper, between 50% and 75% of users attached to cash name fear of fraud among their main reservations.
Four workstreams
- A proportionate regulatory framework: a dedicated status for e-money institutions, lighter identification for small amounts.
- Open infrastructure: direct access to payment systems for non-bank players, as in Ghana, and lower costs for data plans and handsets.
- Uses anchored in daily life: QR-code payments at merchants, micro-savings, advances and insurance suited to irregular incomes.
- Trust and autonomy: data protection laws, security standards, real-time fraud detection, financial education.
Merchant payments are growing: $155 billion in 2025, up 42%, according to the white paper. Flows between bank accounts and wallets exceed $330 billion cumulatively, and 36 instant payment systems were in service across 31 African countries in mid-2025. Only one system in two connects banks, operators and fintechs.
Senegal and the WAEMU in the text
Senegal appears only once, through the example of Orange Bank Africa, which operates in Côte d’Ivoire and Senegal. In 2026 it had more than 3 million customers, had granted more than 640 billion CFA francs in credit since 2020 and collected 585 billion CFA francs in savings through Tik Tak, an offer tied to Orange Money. For the WAEMU, the white paper recalls the BCEAO’s creation of national monitoring committees and names GIM-UEMOA among the regional interoperability platforms.
The text says nothing about Wave. And most of its figures carry no named source: they are the authors’ estimates, to be read as a general snapshot, not as official country-by-country statistics.
- Paiement mobile en Afrique : le défi de l’usage après celui de l’accès, CIO Mag.
- The State of the Industry Report on Mobile Money 2026, GSMA.
Spotted an error? Write to infos@novotech.blog. Corrections are flagged at the end of the article.