Ghana: the boom in digital payments heightens the risk of cyber fraud
Ghana is seeing strong growth in digital payments, driven largely by mobile money. But this transformation is also widening the attack surface for cybercriminals. The authorities want to strengthen the security of the digital financial sector while keeping users’ trust.
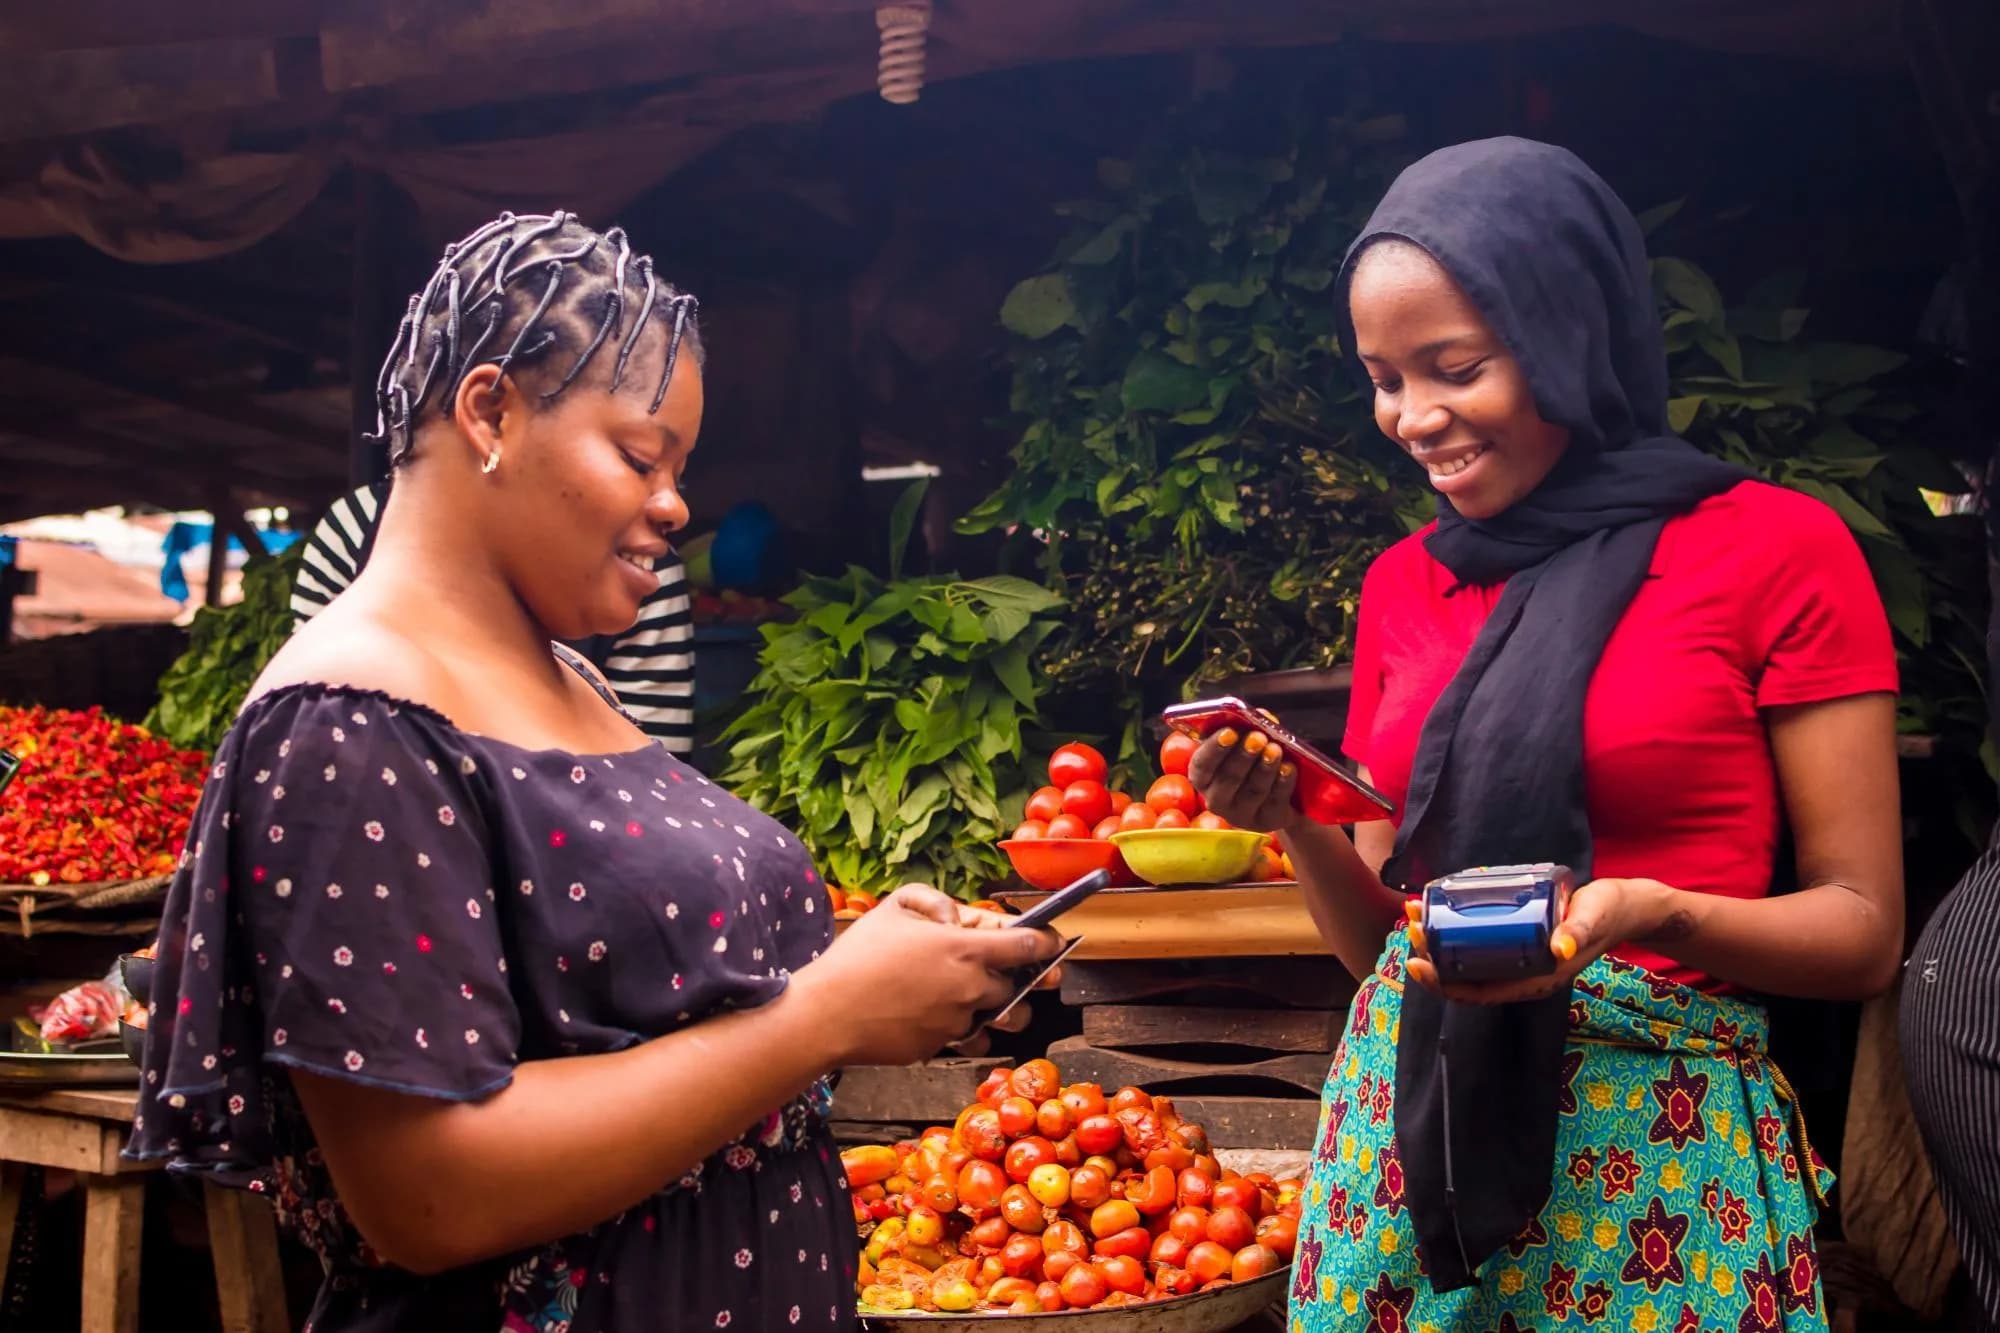
- Ghana’s digital economy is accelerating. In June 2026, e-money balances reached 40 billion cedis, up 38% year on year, while mobile money platforms processed nearly 493 billion cedis in transactions. But between January and July, nearly half of the 3,876 cybersecurity incidents recorded were linked to online fraud.
Mobile money takes on a new dimension
Ghana has become one of the African markets where digital financial services play a major role in everyday life. Mobile money, banking apps, electronic payments and fintech services allow individuals and businesses to make transactions without always relying on cash. This shift is reflected in considerable financial volumes. According to information reported on 3 October by Xinhua, e-money balances in Ghana reached 40 billion cedis in June 2026, an increase of 38% year on year. More than 84 million registered mobile accounts were involved. In the same month, mobile money platforms processed nearly 493 billion cedis in transactions. The network also counted more than one million registered agents for the first time. These figures show how important digital payments have become in Ghana’s economy.
Growth that also widens the attack surface
This digitalisation creates a new problem, however: every new account, every app and every transaction is a potential target for cybercriminals. Ghana’s Cyber Security Authority says 3,876 cybersecurity incidents were recorded between January and July 2026. Of these, 1,818 cases, or about 47%, were linked to online fraud. The Ghanaian authorities cite online fraud, identity theft, payment diversion and business account compromise among the threats targeting the digital financial ecosystem. The problem is therefore no longer confined to the big banks. Fintechs, telecoms operators, merchants and individual users are all affected.
Financial sector figures are also being watched
The CSA’s data show that the problem goes beyond the incidents reported at national level. According to figures from the Bank of Ghana’s 2025 Fraud Report, fraud cases reported to banks, specialised deposit-taking institutions and payment service providers rose from 16,733 in 2024 to 24,778 in 2025, an increase of 48%. The total value of funds at risk reached 101 million cedis. Among payment service providers, electronic fraud incidents rose by 54%, while the value at risk went from 19 to 37 million cedis. These figures cover different periods and should not be added together. They do, however, show digital payment volumes and fraud risks rising side by side.
Ghana wants to make the system more secure
In response, the country has put financial cybersecurity at the heart of its National Cyber Security Awareness Month 2026, which runs throughout October. The chosen theme is: “Securing Ghana’s Digital Finance Ecosystem: Building Trust Through Collaboration and Cyber Resilience” The campaign is built around five pillars: securing digital finance, preventing and responding to cybercrime, protecting critical infrastructure, cyber hygiene, and developing skills and cooperation. The CSA believes cybersecurity must now be seen as a matter of governance and resilience, and not just as the IT department’s responsibility.
Banks cannot act alone
Securing digital payments involves several players. Banks control part of the financial infrastructure. Telecoms operators provide the networks and mobile services. Fintechs develop new platforms, while the authorities handle regulation and coordination. Ghana therefore wants to strengthen information sharing and cooperation between financial institutions, fintechs, telecoms operators, the authorities and law enforcement. This approach can also be seen in the new rules for the financial sector. In September 2026, the Bank of Ghana launched a revised version of its Cyber and Information Security Directive, intended to strengthen the resilience and security of financial institutions.
Artificial intelligence adds a new difficulty
The threat is also evolving with new technologies. The CSA warns that artificial intelligence can be used to produce voice imitations, more convincing phishing messages and more sophisticated social engineering techniques. A fraudster can thus combine several technologies: gather public information about a victim, generate a credible message, impersonate someone and then try to persuade the victim to make a transaction. Payment security therefore no longer depends solely on the banking systems themselves. It also depends on users’ ability to spot attempts at manipulation.
The challenge: keeping trust in digital services
For the Ghanaian authorities, the challenge is twofold: keep developing digital payments while preventing fraud incidents from eroding public trust. The CSA is urging organisations to strengthen identity and access management, use multi-factor authentication, carry out regular vulnerability assessments, protect customer data and improve their incident response capabilities. Ghana’s Interior Ministry also advises users to protect their passwords, PINs and verification codes, to check payment requests and to avoid suspicious links or messages.
A trend that concerns the whole of Africa
Ghana’s experience reaches beyond its borders. As mobile financial services spread across the continent, African businesses will have to develop their digital services and strengthen their cybersecurity at the same time. The challenge is therefore to avoid a situation in which innovation moves faster than protection mechanisms. Ghana is currently trying to tackle this problem by combining regulation, awareness-raising, cooperation between players and stronger security infrastructure.